Independent second opinion · We don't sell policies

For those with a US life insurance policy paid with a loan: let's review the numbers before more money goes in.

Independent audits of premium-financed IUL/UL policies sold in the United States to Latin American families. A clear second opinion, in writing, signed by Pedro Martin. We don't sell policies.

  • Report signed by Pedro Martin
  • Written, in Spanish or English
  • Flat fee, no commissions
  • From Panama, for all of Latin America, Mexico included
Educational guide · In plain language

What is IUL? UL and IUL policies and premium financing, explained

Many Latin American families own a US life policy with documents in English and unfamiliar terms. This guide covers the basics so you can read your policy with more confidence.

1. What is universal life (UL)?

It is permanent life insurance with flexible premiums: within limits, you choose how much and when to pay.

  • Premiums go into a cash value account that the carrier credits with interest.
  • Each month the carrier deducts the cost of insurance (COI), which rises with age, plus other policy charges.
  • Death benefit: Option A (level) or Option B (increasing: face amount plus cash value).
  • If the cash value can't cover the charges, the policy can lapse after a grace period.
  • Some policies carry a no-lapse guarantee (policies built around it are known as GUL), which usually requires paying specified premiums on time.

2. What is indexed universal life (IUL)?

It is UL where the interest credited to the cash value is linked to an index, such as the S&P 500. Your money is not invested directly in the market: the carrier uses options to provide the credit.

  • A floor, often 0%: a negative index year doesn't reduce value by itself, but monthly charges are still deducted.
  • The cap, participation rate and spread limit the credit; the carrier can change them within contract limits.
  • Index dividends are excluded.
  • Credits are usually calculated in annual segments.
  • The illustration shows hypothetical, non-guaranteed rates, subject to US regulatory limits (AG 49 and AG 49-A). Always compare the guaranteed and non-guaranteed columns.

UL and IUL side by side

TopicULIUL
How the cash value growsInterest rate declared by the carrierCredit linked to an index, with a floor and a cap
Guaranteed minimumContract minimum rateContract floor (often 0%)
What the carrier can adjustDeclared rate and charges, within the contractCap, participation, spread and charges, within the contract
Monthly charges (COI and others)YesYes
Can lapse if value runs shortYes, unless a no-lapse guarantee appliesYes, unless a no-lapse guarantee applies

3. Key terms

Cash value / accumulation value
The policy balance after premiums, credits and charges.
Surrender value
What you would receive if you cancel: cash value minus surrender charges (and any policy loans). Those charges usually last 10 to 15+ years.
Cost of insurance (COI)
Monthly charge for the coverage; it rises with age.
Cap
Maximum credit for a segment, even if the index rises more.
Floor
Minimum credit for a segment, often 0%.
Participation rate
The share of the index change used to calculate the credit.
Policy loan
A loan from the carrier secured by the policy value; it accrues interest and reduces the death benefit and surrender value. Different from the bank loan.
Illustration
A projection based on hypothetical assumptions; not a guarantee.
Lapse
The policy ends when its value can't cover the charges.
MEC (Modified Endowment Contract)
A US tax classification triggered by paying premiums above certain limits; it changes how withdrawals and loans are taxed. Consult a tax advisor.

4. How does premium financing work?

Instead of paying large premiums with your own money, a lender (usually a US bank or specialty lender) pays them for you.

  1. The lender pays the premiumto the carrier, on behalf of the policy owner.
  2. The policy is pledgedthrough a collateral assignment to the lender.
  3. Interest is paid or accruedoften variable: SOFR or prime plus a spread.
  4. Periodic collateral reviewif the policy value doesn't cover the balance, more collateral is required.
  5. Planned exitrepay the loan from policy values, other assets or the death benefit.
  • Interest: paid each year or added (accrued) to the loan balance.
  • Collateral call: if the value the lender assigns to the policy is below the loan balance, the lender asks for additional collateral (cash, securities or letters of credit).
  • Renewal: loan terms often renew every few years, and conditions can change.
  • Exit strategy: the sales illustration usually assumes that index credits will outpace loan interest for many years. The plan depends on that spread.

5. Main risks to understand

  • Rising interest rates that make the loan more expensive.
  • Index credits below the illustrated rates.
  • Cost of insurance (COI) increases, up to the contract's guaranteed maximum.
  • Cap reductions or lower participation rates.
  • Collateral calls requiring more collateral or cash.
  • Surrender charges if you exit in the early years.
  • Loan renewal: terms can change, or the loan might not be renewed.
  • English-only documents and complex structures (trusts, companies, several parties) for Spanish-speaking families.

In some cases these structures work as designed. Outcomes depend on the specific contract, the loan terms and actual performance.

6. What we check in an audit

  • Original illustration vs. actual performance: credits, caps, charges and loan rate.
  • Loan balance vs. surrender value vs. required collateral.
  • Stress tests: loan rate +2% and 0% credits for 3 and 5 years.

General educational information; not legal, tax or investment advice. We don't sell policies.

Who it's for

For Latin American families with a USD policy nobody explains anymore

Latin American families and business owners who signed a policy during a US trip (Texas, Florida, California or another state).

Policies funded by a private bank or specialty lender, often with investments or property pledged.

USD IUL owners with policy loans that grow every year.

Attorneys, accountants and bankers who want an independent review for a client.

Warning signs · Free self-check

Check what sounds familiar. Three or more is worth a review.

It takes about 5 minutes. You don't need to send us anything.

Warning signs

Check the signs that apply to you.

Write down your six numbers

With these we can orient you in the free 15-minute triage call. No documents or account numbers.

  1. Loan balance
  2. Current rate (fixed or floating)
  3. Cash surrender value (not just "account value")
  4. Extra collateral requested
  5. Annual premium the loan covers
  6. Death benefit
Three or more checks? Message us to book the free triage call. Go to contact
How it works

Three steps, no pressure

You decide at every step whether to continue.

  1. 1
    Free · 15 min

    Quick triage

    You share six numbers (no documents or account numbers). We tell you where you seem to stand and which documents to gather.

  2. 2
    10 business days

    Express Audit

    We sign an engagement letter with a flat fee. You upload your documents to a secure portal and within 10 business days receive a written report: loan vs. surrender value vs. collateral, stress tests and an options map.

  3. 3
    60 min

    Results call

    We explain what your report means and which questions to ask the carrier, the lender or your attorney.

Founder pricing · introductory

Express Audit: founder offer for the first 10 clients

Introductory launch prices. After the first 10 clients, list prices apply.

Start here

Self-check + quick triage

Free

No commitment

  • 5-minute checklist
  • 15-minute call
  • No documents or account numbers
Start free

Introductory price

Policy without a bank loan

With or without policy loans

US$2,000

Flat fee in US dollars (USD)

  • Written report signed by Pedro Martin
  • Stress tests and options map
  • 60-minute results call
  • Delivered within 10 business days of receiving documents
Request your Express Audit

Payment: 50% upfront, 50% on delivery of the report.

Flat fee in writing in an engagement letter. No commissions from anyone.

Prices and invoicing in US dollars (USD) for clients in any country. Mexico reference only: approx. MXN $37,000 and MXN $74,000 (reference rate: 18.5 MXN per USD); payment is in USD. Introductory prices subject to change.

Not legal or tax advice. No outcome is guaranteed. See disclaimers.

Pedro Martin C.
About

An independent second opinion, in your language

Dictamen de Póliza is a service of Grupo Santa Fe, a company based in Panama, providing independent reviews of US-issued, loan-funded life policies held by clients across Latin America. It was born from something we see more and more: families from Mexico, Central America, the Caribbean and South America with USD policies, documents in English, and collateral calls nobody explains.

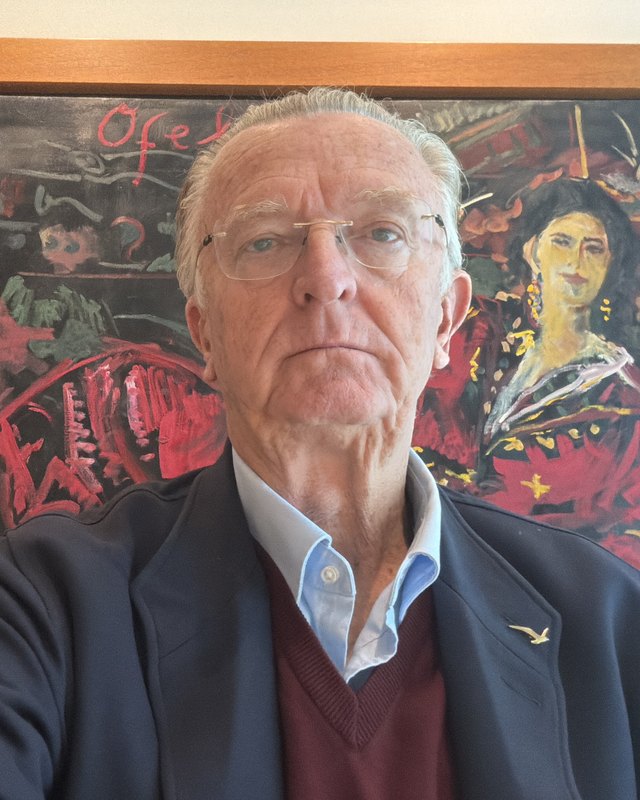
Who signs your report: Pedro Martin C.

For more than thirty years I have seen the real benefits of PPLI and life insurance for estate planning for ultra-high-net-worth families in Latin America.

Premium financing is often the most practical way to buy this kind of coverage. The problem is that the sales process is too often tilted toward the salesperson's commission, not the client. That makes it hard for the owner to know where they stand.

We give you a clear, independent assessment of your policy, for a flat fee, so you can decide whether to keep it, change it, or cancel it.

Background
Over 30 years working with life insurance and PPLI for estate planning for high-net-worth clients in Latin America. Registered insurance broker: LILA, Ltd. (Bermuda), BMA Reg. No. 34780 (since 2005).
License
Registered insurance broker with the Bermuda Monetary Authority · LILA, Ltd. · Reg. No. 34780 (effective 1 September 2005).
Company
Grupo Santa Fe, Panama

Pedro personally signs every audit.

— Pedro Martin C., Grupo Santa Fe
Independence pledge

No commissions. We work only for you.

We don't sell policies or loans. We take no commissions from carriers, agents or lenders. We charge a flat, transparent fee agreed in writing, and we work only for you.

  • No commissions or referral compensation from carriers, agents or lenders on any case we audit.
  • Flat fee in writing, before we start.
  • Plain language, no alarmism.
  • We analyze documents, not people.
  • Confidentiality and a secure portal for your documents.

This pledge is included in writing in every engagement letter.

FAQ

What people ask us most

Are you going to sell me another policy?

No. We don't sell policies or loans and we receive no commissions from carriers, agents or lenders. We only charge a flat fee, in writing.

Do I need to send all my documents to start?

No. Start with six numbers in the free quick triage. If you decide to go ahead, documents are uploaded to a secure portal, never over WhatsApp or email.

Can you tell me whether I have a legal case?

No. We don't give legal opinions. We organize the facts, numbers and timeline so a licensed US attorney can evaluate them.

How long does the Express Audit take?

10 business days from when we receive your documents, followed by a 60-minute results call.

Do you guarantee I'll pay less or recover money?

No. We give you a clear analysis and an options map; the decisions are yours. Results depend on your documents and on carrier and lender data.

How do I pay?

A flat fee agreed in writing: 50% upfront, 50% on delivery. Invoiced in US dollars (USD). Payment methods are listed in the engagement letter.

Do you work with clients outside Mexico?

Yes. We serve clients across Latin America from Panama, Mexico included. The service is remote: calls, email and a secure portal for documents. Reports are delivered in Spanish, with an English copy available.

What happens to my information?

We keep it confidential and ask only for what's needed. Documents are received only through a secure portal. See the Privacy Notice.

Contact

Request your Express Audit

Tell us the basics and we'll reply within 1 business day to book your free quick triage.

Don't send documents, account numbers or passwords over WhatsApp, email or this form. If we move forward, we'll share a secure portal.

Intake form

Submitting opens your email app with your answers, addressed to [email protected]. Don't attach documents.

Privacy: Grupo Santa Fe (Panama) is responsible for your data. We use it to answer your request and, if you hire us, to provide the service. You can exercise your rights of access, rectification, cancellation, objection and portability by emailing [email protected] with the subject "Protección de datos". Details in the Privacy Notice.

WhatsApp